
How Much Cash Eastern Metro Home Buyers Actually Need at Closing
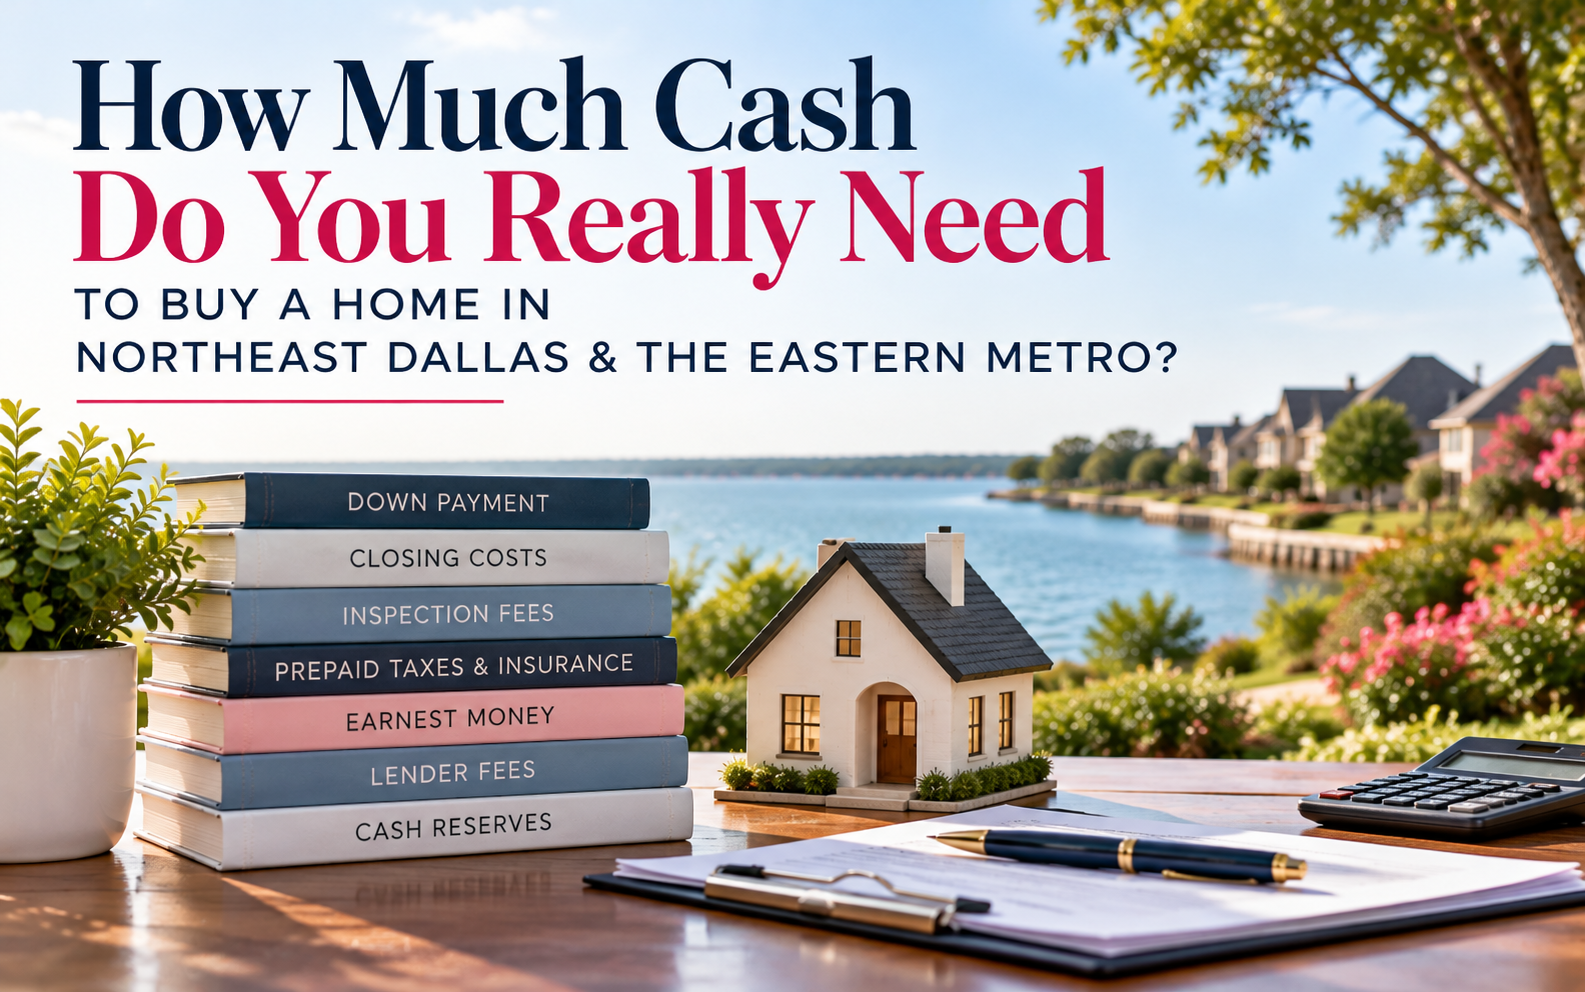
Buying a home in Northeast Dallas and the Eastern Metro requires more cash than the down payment alone. Budget for closing costs, prepaid insurance and taxes, inspection fees, earnest money, and lender-required reserves. The exact total depends on your loan program, purchase price, closing date, and negotiated seller credits.
How much cash do you actually need to buy a home in Northeast Dallas and the Eastern Metro?
Buying a home in the Eastern Metro, Rowlett, Rockwall, Wylie, Sachse, Lavon, Murphy, or anywhere across Northeast Dallas, requires more cash than the down payment alone. Your total funds at closing typically include the down payment, lender and title-company charges, prepaid homeowners insurance and property taxes, inspection fees paid before closing, earnest money already delivered, and any cash reserves your lender requires you to keep after the transaction funds. The exact number depends on your loan program, purchase price, negotiated credits, and the date you close.
Key Takeaways
- The DFW median list price was $425,000 in August 2026, down 1.2% year over year, according to Realtor.com's August 2026 market report, metro-wide context, not a city-specific figure for Rowlett, Wylie, or Rockwall.
- Earnest money in a Texas transaction is held by the title company and credited toward your funds at closing, it is not a separate cost on top of everything else.
- Texas does not impose a general state real-estate transfer tax, so that line item does not belong in your cash calculation.
- Your closing date affects how much prepaid mortgage interest and initial escrow funding you owe, a date early versus late in the month can shift your cash-to-close figure meaningfully.
- Communities in the Eastern Metro span multiple counties and appraisal districts; the exact address determines your taxing jurisdictions, not just the city name.
What is actually included in your cash to close in the Eastern Metro?
"Cash to close" is the number on your Closing Disclosure, the document your lender provides before settlement that itemizes every dollar you owe at the table. It is broader than the down payment, and in my experience working with buyers across the Eastern Metro, the gap between what people expect and what they actually need at closing is one of the most common surprises in the process.
Here is how the pieces stack up, in the order you encounter them:
Earnest money
Earnest money is a contract deposit you deliver after your offer is accepted, held by the title company. In Texas, it is a negotiated amount, there is no universal rule about what percentage it must be. The important thing to understand: it is credited against your funds at closing, so it is not an additional cost on top of everything else. You are paying it early, not paying it twice.
Inspection and due-diligence expenses
These are paid before closing and typically do not appear as a line item on your Closing Disclosure. A general home inspection is the baseline, but in the Eastern Metro you may also need roof, HVAC, foundation, sewer, or pool inspections depending on the property. Properties near Lake Ray Hubbard or Lake Lavon may warrant additional diligence around flood exposure, drainage, retaining structures, docks, seawalls, and easements. I never tell a buyer to skip an inspection because a home looks well-maintained, pretty finishes do not tell you what is happening behind the walls or under the slab. For a deeper look at what to watch for in North Texas specifically, Foundation Issues in North Texas: What Buyers and Sellers Need to Know is worth reading before you make an offer.
Down payment
Your down payment is determined by your loan program. Conventional loans can go as low as 3% for qualifying buyers; FHA loans require 3.5% with qualifying credit; VA and USDA loans have zero-down options for eligible borrowers. A 20% down payment eliminates private mortgage insurance but is not a requirement. If you are working with a tighter cash position, Texas Down Payment Assistance: What Rockwall and DFW Buyers Need to Know outlines programs that may apply to your situation.
Lender and title-company charges
These include origination fees, appraisal, credit report, underwriting, and related lender costs, plus title insurance premiums and title-company charges for escrow, examination, recording, and coordination. In Texas, title-insurance premium rates are regulated by the Texas Department of Insurance rather than freely negotiated like ordinary service fees, but the title company may also charge separate escrow, courier, and transaction fees that are not part of the regulated premium. Ask for an itemized preliminary settlement statement early so none of this catches you off guard.
Prepaids: insurance, interest, and initial escrow deposits
Prepaid items are costs you pay at closing that cover the period immediately after you own the home. They typically include:
- Prepaid homeowners insurance, usually a full year's premium paid upfront at or before closing
- Prepaid mortgage interest, interest from your closing date through the end of that month; closing early in the month means more days of prepaid interest, closing near month-end means fewer
- Initial escrow deposit, your lender funds a cushion for future property-tax and insurance bills; the amount depends on the lender's escrow analysis, your closing date, and taxes already paid or prorated
If the property is in a designated flood-hazard area, your lender may also require flood insurance, which adds a separate prepaid and ongoing escrow component. Verify the flood-zone status of any property before you treat your required cash as a known number.
Property-tax prorations
Texas property taxes are paid in arrears, so at closing the seller typically credits the buyer for the portion of the year the seller owned the home. That credit reduces your cash at closing rather than adding to it, but your lender will still collect an initial escrow deposit to cover future bills. The Dallas County Tax Office notes that the Eastern Metro communities span multiple appraisal districts: Dallas Central, Collin Central, and Rockwall Central, depending on the exact address. Rowlett straddles Dallas and Rockwall counties; Wylie, Sachse, and Murphy can involve Dallas or Collin County boundaries; Lavon is in Collin County; Rockwall is in Rockwall County. The address, not just the city name, determines your taxing jurisdictions.
Seller credits and lender credits
In a market where 27.5% of DFW listings carried a price reduction as of August 2026 and the median days on market was 58 days, buyers have more room to negotiate than they did two or three years ago. Seller-paid closing costs are a legitimate negotiating tool, and in the right transaction they can meaningfully reduce the cash you need at the table. Lender credits are another option, you accept a slightly higher rate in exchange for a credit toward closing costs. Both are worth discussing with your agent and lender before you make an offer. For more on navigating this market as a buyer, see How Dallas Buyers Can Win in a Softening 2026 Market.
What cash reserves does a lender require after closing?
Some loan programs require you to demonstrate that you will still have funds remaining after closing, typically expressed as a certain number of months of mortgage payments. This is separate from your cash to close. The requirement varies by loan type, property type, and lender, so confirm the reserve requirement with your lender early in the process.
The practical implication: your total cash position going into a purchase needs to cover the down payment, closing costs, prepaids, inspection fees paid before closing, and whatever reserve the lender requires you to keep afterward. That is the real number to plan around, not just the down payment in isolation.
| Cash Component | When You Pay It | Notes |
|---|---|---|
| Earnest money | After contract execution | Held by title company; credited at closing |
| Inspection fees | During option/due-diligence period | Paid directly to inspectors; not on Closing Disclosure |
| Down payment | At closing | Determined by loan program; various amounts available |
| Lender charges | At closing | Origination, appraisal, underwriting, credit report |
| Title-company charges | At closing | Title insurance (regulated), escrow, recording, examination |
| Prepaid insurance | At or before closing | Typically a full year's premium upfront |
| Prepaid mortgage interest | At closing | Closing date affects the number of days owed |
| Initial escrow deposit | At closing | Funds future tax and insurance payments |
| Property-tax proration | At closing | Usually a seller credit to buyer; closing date dependent |
| Post-closing cash reserves | Must remain after closing | Lender requirement; varies by loan program |
A note on the Texas homestead exemption and what it does not do at closing
After you close, you can file for a homestead exemption with the appraisal district that serves your property. The City of Dallas property-tax guidance notes that completed exemption applications should generally be filed before May 1 of the year following your purchase. The exemption can reduce your property-tax bill going forward, but it does not change the amount on your initial Closing Disclosure and does not eliminate the need to fund tax prorations or your lender's escrow deposit at closing. Think of it as prospective planning, not an immediate closing credit.
Your specific cash-to-close number is something I walk every buyer through before we start making offers, because the only way to know the real figure is to run it with your lender and get a Loan Estimate in hand. According to the Consumer Financial Protection Bureau's "Know Before You Owe" guidance, lenders are required to provide a Loan Estimate early in the application process and a Closing Disclosure before closing. Those two documents are your controlling numbers, not any estimate you read online.
If you want to know what your cash position needs to look like before you start seriously searching in Rowlett, Wylie, Sachse, Lavon, Murphy, or Rockwall, let's talk through it. The earlier we have that conversation, the fewer surprises show up at the closing table.
If you would like to read what buyers and sellers across the Eastern Metro have said about working with our team, you can find our reviews on Google, Zillow, and Realtor.com.
Frequently Asked Questions
How much cash do I need to buy a house in Rowlett, Garland, or Rockwall?
The total cash needed depends on your purchase price, loan program, closing date, and what you negotiate with the seller, there is no single number that applies to every buyer. Your lender's Loan Estimate will give you the most accurate projection once you have a property in mind. Plan for the down payment, lender and title-company charges, prepaid insurance and taxes, inspection fees, and any post-closing reserves your lender requires.
Can earnest money be used toward my down payment and closing costs in Texas?
Yes. In a Texas transaction, earnest money is held by the title company and credited against the funds you owe at closing, so it reduces the remaining cash you bring to the table. It is not charged again as a separate closing cost, you are paying it early, and it counts toward your total.
When do I pay earnest money after my offer is accepted?
In Texas, the timing for delivering earnest money is set by the contract and is typically within a few days of contract execution. The exact deadline is negotiated and written into the purchase agreement, so review your contract carefully. The title company holds the funds until closing or until the contract is terminated according to its terms.
What is included in "cash to close" on the Closing Disclosure?
Cash to close is the total funds you need to bring to the title company on closing day, and it includes the down payment, lender charges, title-company charges, prepaid homeowners insurance, prepaid mortgage interest, initial escrow deposits for taxes and insurance, and any remaining balance after seller credits and your earnest money are applied. The CFPB's Closing Disclosure guidance explains each line item in detail.
Can the seller pay some of my closing costs in a Texas home purchase?
Yes, seller-paid closing costs are negotiable in a Texas transaction and are a common tool in the current Eastern Metro market, where days on market have stretched and price reductions are more common than they were a few years ago. Whether a seller agrees to contribute, and how much, depends on the contract negotiation, the loan program's limits on seller contributions, and market conditions at the time of your offer.
Do I need an inspection before buying a home in Wylie, Sachse, Lavon, or Murphy?
No law requires an inspection, but skipping one is a risk I consistently advise against. North Texas soil conditions, foundation movement, and aging HVAC systems are real factors across the Eastern Metro, and a general inspection may need to be supplemented by a foundation, roof, or sewer inspection depending on the property's age and condition. Properties near Lake Lavon may also warrant additional diligence on drainage, flood exposure, and easements.
Do I need separate reserves for flood insurance near Lake Ray Hubbard or Lake Lavon?
If the property or its improvements are in a designated flood-hazard area, your lender may require flood insurance, which adds both an upfront prepaid premium and an ongoing escrow component to your costs. Verify the property's flood-zone status before you treat your required cash as a final number, and ask your insurance agent about coverage availability, deductibles, and exclusions specific to that address.
Your cash position is one of the most important things to nail down before you start making offers. Book a consultation with The Dunnican Team and we will walk through what your numbers actually look like for the Eastern Metro communities you are targeting.
About Cindy Dunnican
Cindy Dunnican is the Founder and Managing Partner of The Dunnican Team at Coldwell Banker Apex, Realtors, serving Northeast Dallas, Rockwall County, and surrounding North Texas communities including Rockwall, Rowlett, Heath, Wylie, Sachse, Fate, Royse City, and Caddo Mills. With 28+ years of experience, 1,850+ transactions, and recognition as a D Magazine D Best honoree every year since 2010, Cindy leads listings, marketing, and brand strategy for the team. She and her husband Cory Dunnican are both Global Luxury Certified and Real Trends Verified. Reach The Dunnican Team at 972-679-1789 or www.TheDunnicanTeam.com.
Coldwell Banker Apex, Realtors · 9726791789
Equal Housing Opportunity. Cindy Dunnican is a licensed real estate salesperson in Texas, regulated by the Texas Real Estate Commission (TREC). This article is general information only and is not legal, tax, or financial advice. Confirm your specific closing costs, tax obligations, and cash requirements with your title company, lender, and tax advisor.
Check out this article next
Prep Improvements That Help Rockwall Homes Sell Closer to Asking Price
In Rockwall's current buyer's market, the most cost-effective pre-sale improvements focus on visible maintenance, neutral paint, functional repairs, and modest kitchen or bathroom refreshes, not…
Read Article