
DFW's New Construction Market Builder Incentives Explained
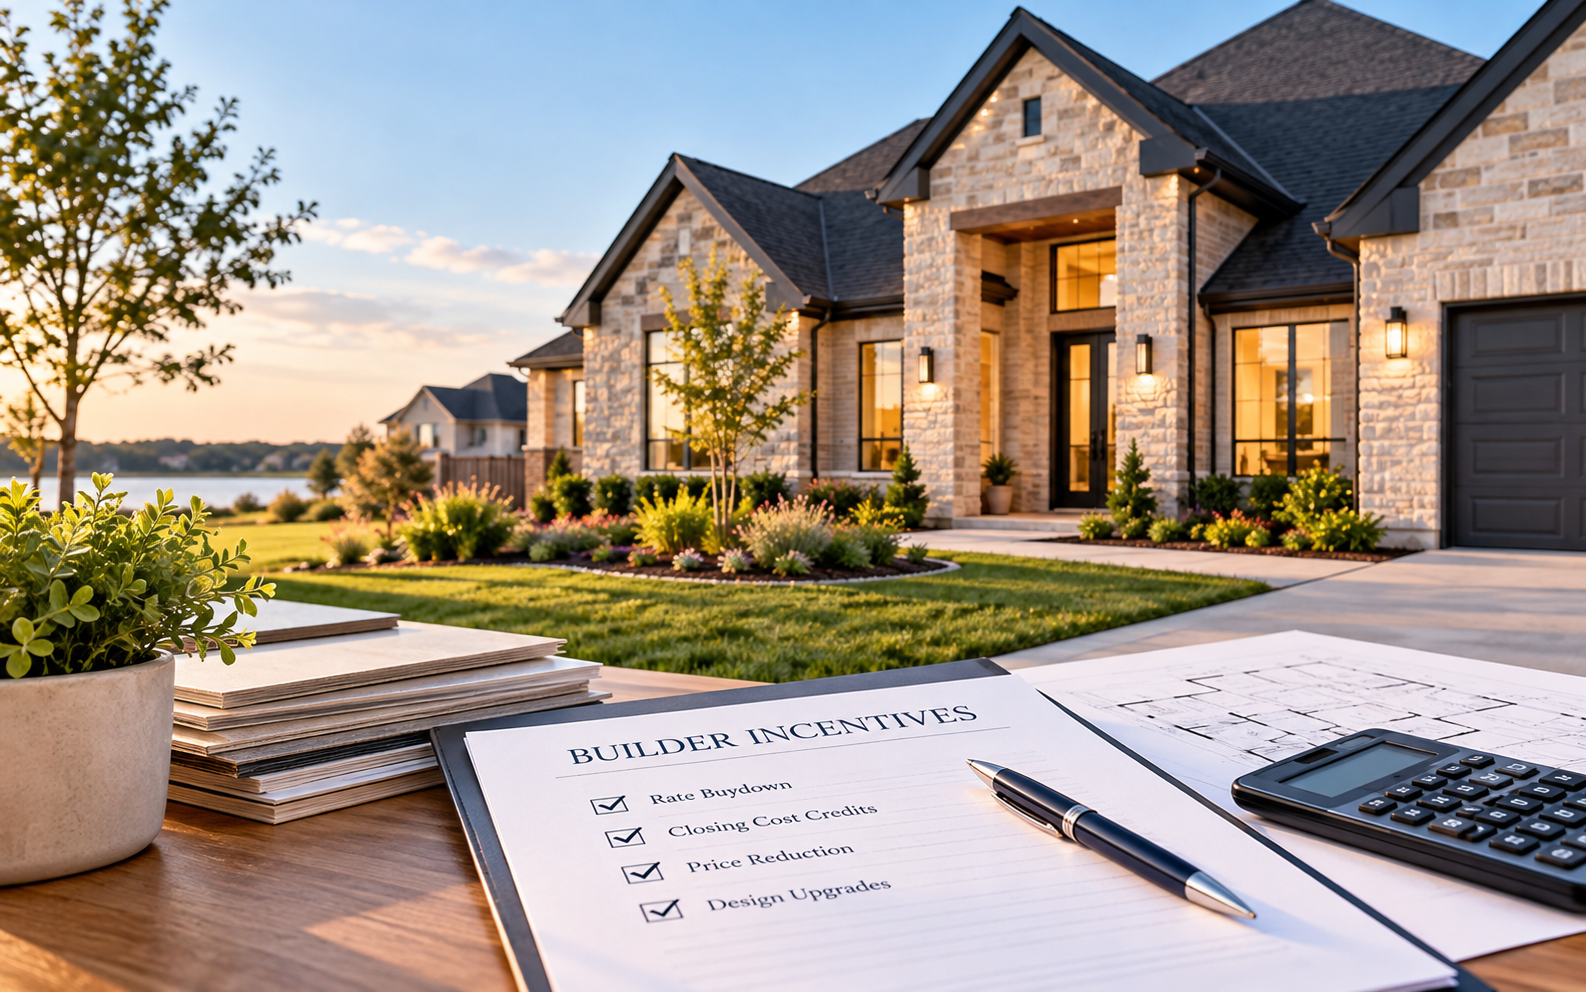
Builder incentives in DFW's New Construction Market are concessions like rate buydowns, closing-cost credits, price reductions, and design upgrades. Their value depends on the written terms, not the headline. A national survey found 65% of builders using incentives in October 2026, so compare each offer against a price cut and outside financing before signing.
DFW's New Construction Market Builder Incentives Explained
How do builder incentives work in DFW's New Construction Market?
Builder incentives in DFW's New Construction Market are contractual concessions, such as a rate buydown, a closing-cost credit, a price reduction, or included design upgrades, and each one is only worth what the written terms say. A national survey reported in October 2026 found that 65% of builders were using sales incentives, so you should expect an offer to be on the table. Your job is to compare the whole package against a straight price cut and against financing from an outside lender.
Key Takeaways
- A national survey reported by NBC 5 Dallas–Fort Worth found 65% of builders were using sales incentives in October 2026, the 19th straight month at 60% or higher.
- The same survey found 43% of builders had cut prices, with an average reduction of 6%, though that is national data and not a DFW measurement.
- A temporary rate buydown lowers your payment only during its introductory period and does not necessarily lower the permanent note rate.
- Incentives can differ between communities even when the same builder is selling in both, so confirm each offer in writing for the specific community and home.
- Eligibility, required lender or title company, and closing deadlines live in the builder's written addendum, and that document decides whether you actually keep the incentive.
What builder incentives are showing up in DFW's New Construction Market?
Most offers fall into four buckets: financing help, closing-cost credits, price reductions, and design or feature upgrades. Builders often mix them, which is why two offers that look similar on a flyer can be very different on paper.
The pressure behind them is real. NBC 5 Dallas–Fort Worth reported that 65% of builders nationally were using sales incentives in October 2026, and that 43% had reduced prices by an average of 6%. That is a national snapshot, not a Rockwall or Lake Lavon number. It does tell you that builders are competing for buyers, and that gives you room to ask questions.
Rate buydowns
A buydown trades an upfront cost, paid by the builder, for a lower interest cost to you. A temporary buydown lowers your payment for an introductory period, then the payment steps up. A permanent buydown works differently. Always ask which one you are being offered, because the headline rate and the long-term payment are not the same thing.
Closing-cost credits
A credit offsets certain closing costs, usually with conditions attached. Those conditions may include which lender or title company you use and the date you close. I cover that tradeoff in my post on the builder's title company versus your own in Texas new construction.
Price reductions and lot premiums
A price reduction lowers the contract price itself. Ask how the builder is treating any lot premium too. A lake-adjacent or premium homesite can change the math on an offer that looks generous.
Design-center upgrades and included features
Upgrade packages feel valuable because you pick them yourself. Ask which features are included at no charge and which ones you would otherwise be paying for. A feature you would not have chosen is not a savings.
How do I compare a builder incentive with a price cut or outside financing?
Compare the payment after any temporary period ends, the cash you need at closing, and your total contractual obligations, not the headline rate. A builder incentive that looks great on day one can lose to a plain price reduction or to a loan from your own lender.
| Incentive type | What it does | What to compare it against |
|---|---|---|
| Temporary rate buydown | Lowers your payment during an introductory period | Your projected payment after the temporary period ends |
| Permanent rate buydown | Lowers the cost of the loan on an ongoing basis | The Loan Estimate from an outside lender |
| Price reduction | Lowers the contract price of the home | The cash you need at closing and the total you owe |
| Closing-cost credit | Offsets certain closing costs under stated terms | Whether the credit is tied to a required lender or title company |
| Design-center upgrades | Adds features to the home | Whether you would have paid for those features anyway |
Get a Loan Estimate from the builder's lender and one from an outside lender on the same loan program, then lay them side by side. The Consumer Financial Protection Bureau publishes plain-language guidance on reading that form. Your own lender is also the right person to confirm how any credit or buydown fits your loan program.
Your best choice depends on how long you plan to stay, how much cash you want to keep, and what you will actually use. That is the kind of comparison I run with my clients before they ever sign a contract.
Why the builder's sales representative is not your advocate
New construction can be a strong value, but the person across the table works for the builder. I want my buyers to have someone looking out for their side, especially when the incentive is complicated and tied to deadlines.
What should a builder incentive have in writing before I sign?
Get the entire offer in writing, in the contract or an addendum, before you sign anything. Verbal promises and a sales-center banner do not protect you if something changes.
Here is what I ask builders to put on paper for my buyers:
- The base price and any price reduction
- How lot premiums are treated
- Included structural and design features
- Lender credit or rate-buydown terms
- Title or closing-cost credit terms
- Any required lender, title, insurance, or closing provider
- Minimum loan amount, credit score, occupancy, and loan-program conditions
- The contract date and the closing deadline
- What happens to the incentive if construction or closing misses that deadline
The last two matter more than buyers expect. If the incentive expires on a date and the home is not finished by then, you need to know who bears that risk before you are committed. Incentives are not a statewide benefit or a fixed amount. Eligibility, permitted uses, lender underwriting, and expiration dates are set by the builder's written terms and your loan documents.
Closing in Texas runs through a title company, so make sure the title company's role is clear in the incentive language. If you are also thinking about the long game, my post on new construction taxes in Rockwall County and the year-two jump will help you look past the first-year payment.
Do builder incentives apply in Rockwall, Fate, Royse City, and around the lakes?
Not automatically. An advertised offer is usually specific to a builder, a community, and sometimes a single home, so you cannot assume it carries across communities in Rockwall, Fate, Royse City, Forney, Wylie, or Lavon, or to any development near Lake Ray Hubbard or Lake Lavon.
I would not trust a corridor-wide incentive range, and you should not either. There is not one DFW market, and the same builder can run different offers in neighboring communities. Confirm what applies directly with the sales office, in writing, for the exact home you want.
If you are weighing a specific community, start with my guide to buying new construction near Rockwall. If Royse City is on your list, read about whether you need your own agent there. Every situation here is different, and the only way to know what an offer is worth to you is to put the numbers next to your plans with someone who knows these communities. That is what I do for my buyers.
If you are a move-up buyer who needs to sell a current home to fund a new build, the timing of your sale and the builder's closing deadline need to line up. Start with a free home valuation so that part of the plan is not a surprise later.
Want to see how you compare to other buyers? Read what clients say about working with me on Google, Zillow, and Realtor.com.
FAQ
Do I have to use the builder's lender to receive the incentive?
Sometimes, but not always, and the answer is in the builder's written terms. Many incentives are tied to a preferred lender or title provider. Ask for the requirement in writing and get a Loan Estimate from an outside lender so you can see what you would be giving up.
Is a builder's low mortgage rate better than taking a price reduction?
It depends on the structure and on how long you plan to own the home. A temporary buydown can lower your payment early on without necessarily lowering the permanent note rate, while a price reduction lowers the contract price outright. Compare your payment after any introductory period and your cash required at closing.
Can I negotiate a builder incentive on a completed inventory home?
You can ask, and it is often worth asking, but nothing is guaranteed. Builders can treat completed homes differently from homes not yet built, and each builder has its own approach. I look at how long the home has been available and what the builder is offering on comparable homes before we make a request.
Should I choose closing-cost credits, a rate buydown, or design-center upgrades?
Choose based on what you will use and how long you will stay. A credit helps with cash at closing, a buydown helps with the payment, and upgrades add features you would otherwise pay for. Run each against a straight price reduction before deciding.
What happens to the incentive if my closing is delayed?
That should be spelled out in your contract or addendum. Ask before you sign what happens to the incentive if construction or closing misses the deadline, and who bears that risk. If the answer is vague, it is a reason to slow down and get clarity.
Ready to compare an offer?
The builder's incentive is a starting point, not the finish line. My team and I will help you compare the package, line it up against outside financing, and make sure the paperwork matches the promise. Call The Dunnican Team at 972-679-1789 or visit TheDunnicanTeam.com to talk through the new construction offer you are considering.
About Cindy Dunnican
Cindy Dunnican is the Founder and Managing Partner of The Dunnican Team at Coldwell Banker Apex, Realtors, serving Northeast Dallas, Rockwall County, and surrounding North Texas communities including Rockwall, Rowlett, Heath, Wylie, Sachse, Fate, Royse City, and Caddo Mills. With 28+ years of experience, 1,850+ transactions, and recognition as a D Magazine D Best honoree every year since 2010, Cindy leads listings, marketing, and brand strategy for the team. She and her husband Cory Dunnican are both Global Luxury Certified and Real Trends Verified. Reach The Dunnican Team at 972-679-1789 or www.TheDunnicanTeam.com.
Coldwell Banker Apex, Realtors · 9726791789
Equal Housing Opportunity. Cindy Dunnican, Salesperson, regulated by the Texas Real Estate Commission (TREC). This article is general information, not legal, tax, or financial advice. Confirm your own numbers with your title company, tax advisor, or lender.
Check out this article next
Launching Your Home with Cindy Dunnican's Pricing in DFW
Launching your home with Cindy Dunnican's pricing strategy means setting the list price from closed sales, active competition, and pending contracts in your specific micro-market,…
Read Article